Loan Against Mutual Funds Calculator: कितना Loan मिलेगा और कितना Interest देना होगा?
Mutual Fund बेचने के बजाय उसके against loan लेने का सोच रहे हैं? यहाँ जानें loan amount, LTV ratio, interest calculation और जरूरी risks—एक आसान calculator के साथ।
कभी-कभी अचानक पैसों की जरूरत पड़ जाती है—जैसे medical expense, घर का जरूरी काम या कुछ समय के लिए cash flow की परेशानी। ऐसे में अगर आपके पास Mutual Fund investments हैं, तो उन्हें तुरंत redeem करना ही एकमात्र option नहीं है। कुछ banks और NBFCs आपके eligible mutual fund units को pledge करके loan या overdraft facility देते हैं।
Loan Against Mutual Funds Calculator आपको समझने में मदद करता है कि आपके investment के आधार पर लगभग कितना loan मिल सकता है और उस रकम पर कितना interest बन सकता है। हालांकि, final amount और rate lender की policy, eligible scheme और आपकी application पर निर्भर करेंगे।
1. Loan Against Mutual Funds क्या है?
Loan Against Mutual Funds (LAMF) एक secured credit facility है। इसमें आप अपने eligible mutual fund units को lender के पक्ष में pledge या lien mark करते हैं। इसके बदले lender आपको एक तय borrowing limit दे सकता है। कई products overdraft के रूप में होते हैं, जिसमें आप जरूरत के अनुसार रकम निकालते हैं।
इसका एक बड़ा अंतर यह है कि आमतौर पर units तुरंत बेचने की जरूरत नहीं होती। आप investment में बने रह सकते हैं, लेकिन pledged units पर restrictions रहती हैं। जब तक dues और lender की शर्तें पूरी नहीं होतीं, आप उन units को सामान्य रूप से redeem या transfer नहीं कर पाएँगे।
2. Loan Against Mutual Funds Calculator इस्तेमाल करें
नीचे अपनी mutual fund value, fund category, अनुमानित LTV, interest rate और जितने समय के लिए रकम चाहिए वह भरें। Calculator संभावित loan limit और अनुमानित simple interest दिखाएगा।
🧮 LAMF Calculator
Calculation देखने के लिए button दबाएँ।
यह educational estimate है, loan approval या lender quote नहीं। इसमें processing fee, GST, अन्य charges, changing balance और compounding शामिल नहीं हैं।
3. कितना Loan और Interest देना होगा? Example
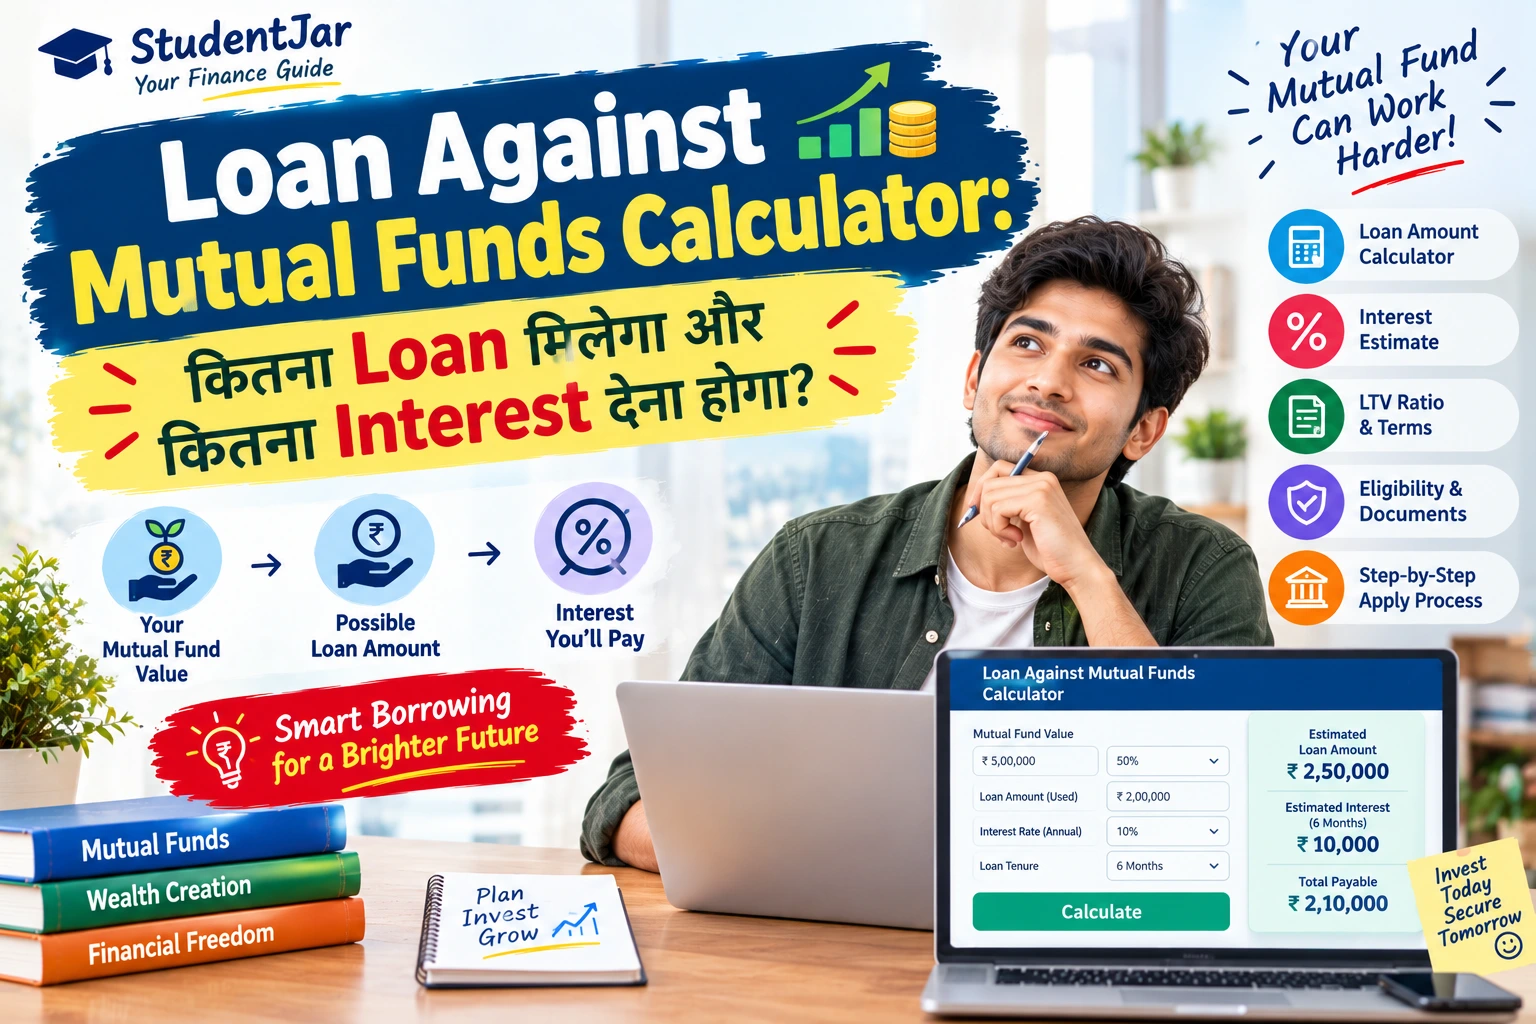
मान लीजिए आपके पास ₹5,00,000 की eligible mutual fund holdings हैं। केवल समझाने के लिए 50% LTV मानते हैं। ऐसे में indicative borrowing limit ₹2,50,000 होगी। अगर आप पूरी limit के बजाय ₹2,00,000 इस्तेमाल करते हैं और illustrative interest rate 10% सालाना है, तो छह महीने का simple-interest estimate होगा:
| Calculation | Amount |
|---|---|
| Eligible mutual fund value | ₹5,00,000 |
| Illustrative LTV | 50% |
| Estimated maximum limit | ₹2,50,000 |
| Amount actually used | ₹2,00,000 |
| Interest at 10% for 6 months | ₹10,000 |
| Principal + estimated interest | ₹2,10,000 |
यह सिर्फ example है। आपका lender कम या ज्यादा LTV दे सकता है, और processing fees या taxes अलग से लग सकते हैं। अगर facility overdraft है, तो कई products में interest पूरे sanctioned limit पर नहीं बल्कि इस्तेमाल की गई रकम और उसके outstanding रहने के समय पर लगता है।
4. LTV Ratio क्या होता है?
LTV यानी Loan-to-Value ratio यह बताता है कि eligible investment value के मुकाबले कितने प्रतिशत तक borrowing limit मिल सकती है। उदाहरण के लिए, ₹4 लाख की eligible holdings पर 50% LTV हो तो estimated limit ₹2 लाख होगी।
कुछ lenders equity, hybrid और debt funds के लिए अलग margins रखते हैं। उदाहरण के लिए, Federal Bank की LAMF जानकारी equity/hybrid और debt holdings के लिए अलग LTV limits बताती है। दूसरे lenders की policy अलग हो सकती है।
5. Interest Rate और दूसरे Charges
Loan की cost सिर्फ interest rate से तय नहीं होती। Application करने से पहले ये बातें जरूर check करें:
- Interest rate: Annual rate, calculation method और rate fixed है या बदल सकती है।
- Processing fee: कुछ lenders fixed fee लेते हैं, जबकि कुछ sanctioned amount या limit का percentage लेते हैं।
- GST और statutory charges: लागू taxes और pledge-related charges हो सकते हैं।
- Renewal fee: Overdraft facility को आगे जारी रखने पर renewal charge लग सकता है।
- Late payment / default charges: Due amount समय पर नहीं चुकाने पर अतिरिक्त cost हो सकती है।
Current terms देखने के लिए ICICI Bank LAMF details और SBI YONO LAMF details compare करें। Advertised rate को अपने लिए guaranteed rate न मानें; final offer और Key Fact Statement देखें।
6. Loan Against Mutual Funds कैसे लें?
- ऐसा bank या NBFC चुनें जो आपकी mutual fund scheme accept करता हो।
- Minimum/maximum loan, LTV, interest rate और fees check करें।
- Application में personal details, PAN और आवश्यक bank/investment information दें।
- Eligible mutual fund units को lender के पक्ष में pledge या lien mark करें।
- Sanctioned limit, repayment terms और applicable charges पढ़ने के बाद ही agreement accept करें।
- जरूरत के अनुसार रकम इस्तेमाल करें और interest/payment schedule track करते रहें।
Eligibility और process lender के अनुसार अलग हो सकते हैं। आवेदन करने से पहले उसकी official website और loan documents पढ़ना बेहतर है।
7. फायदे और Risks जो आपको जानने चाहिए
Possible Benefits
- पैसों की जरूरत के लिए eligible investments तुरंत बेचने की जरूरत नहीं पड़ सकती।
- Overdraft में जरूरत के अनुसार रकम इस्तेमाल करने की सुविधा मिल सकती है।
- कुछ products में utilised amount और अवधि के आधार पर interest लगता है।
Important Risks
- Market गिरने से NAV और eligible borrowing limit कम हो सकती है।
- Margin shortfall होने पर अतिरिक्त repayment या collateral की जरूरत पड़ सकती है।
- Default या lender की शर्तें पूरी न होने पर pledged units बेची जा सकती हैं।
- Investment return guaranteed नहीं है, जबकि loan interest और repayment obligations बने रहते हैं।
Mutual fund investment risks समझने के लिए AMFI का investor education page देखें। केवल इसलिए loan न लें कि limit उपलब्ध है—पहले repayment capacity जाँचें।
8. FAQs – अक्सर पूछे जाने वाले सवाल
Q1. Loan Against Mutual Funds Calculator क्या बताता है?
यह eligible investment value और चुने गए LTV के आधार पर indicative loan limit निकालता है। Interest estimate के लिए loan usage, rate और duration भी शामिल करता है।
Q2. ₹1 लाख के mutual fund पर कितना loan मिल सकता है?
यह fund type और lender की policy पर निर्भर है। उदाहरण के लिए, 50% illustrative LTV पर ₹1 लाख की eligible holdings से ₹50,000 की estimated limit बनेगी।
Q3. क्या पूरे sanctioned loan पर interest देना होता है?
Overdraft products में interest अक्सर इस्तेमाल की गई outstanding रकम पर लगता है। Exact calculation method अपने lender के agreement में check करें।
Q4. क्या mutual fund units redeem कर सकते हैं?
Pledged units पर lien या pledge होने के दौरान redemption restricted हो सकता है। Units release करने के लिए lender की applicable conditions पूरी करनी पड़ती हैं।
Q5. क्या equity और debt funds पर एक जैसा loan मिलता है?
जरूरी नहीं। LTV, approved scheme list और loan limits fund category और lender के अनुसार अलग हो सकते हैं।
Q6. क्या interest rate हर bank में समान होता है?
नहीं। Rate borrower profile, collateral, product और lender की current policy पर निर्भर करता है। Apply करने से पहले interest के साथ सभी charges compare करें।
Conclusion
Loan Against Mutual Funds Calculator आपको loan limit और estimated interest का शुरुआती अंदाजा देता है। लेकिन सही फैसला लेने के लिए LTV, actual interest rate, processing fees, repayment terms और market risk को एक साथ देखना जरूरी है। अलग-अलग lenders के official offers compare करें और उतना ही loan लें जिसे समय पर repay कर सकें।
StudentJar पर अन्य guide: Dr Ambedkar Scholarship Form – Eligibility और आवेदन की जानकारी.
1 thought on “Loan Against Mutual Funds Calculator: कितना Loan मिलेगा और कितना Interest देना होगा?”